
The shift to remote and hybrid work in many industries, aided by technological advances in video conferencing, has created seismic repositioning of traditional office space as an asset class.
With frequent stories of office-building fire-sales at prices well under what the last owner paid for them, and vacancy/availability rates between 20-25%, the office apocalypse might look close at hand, if not already here.
Add in the popularity of remote work and proliferation of freelancers, and the precipitous growth of coworking spaces over the last decade and a half makes sense. Instead of signing an expensive multi-year lease, a coworking facility allows a company or an individual to access office space and related amenities as needed by paying monthly membership fees.
The growth rate for the shared-office industry was nearly 20% in 2022, and is expected to sustain a 17.8% compound yearly growth rate through 2026 according to a whitepaper by Yardi Systems, a property management software and services company.
Do such numbers represent a sea-change in offerings in the market and a serious disruption of business-as-usual for brokers? Let’s look at some of the numbers and check in with a local expert.
National and local trends
Among the top 50 Metropolitan Service Areas (MSAs) tracked by Yardi, 34 saw an increase in coworking inventory in Q1 2025.
Nationally, the number of coworking spaces in the US market grew 2% over the first quarter, from an inventory of 7,695 spaces recorded at the close of last year to 7,840 at the beginning of April 2025.
Salt Lake City’’s number of coworking spaces remained flat in Q1. Yardi counted 81 flex workspaces, unchanged from the previous quarter. In Q4 2024 that number in Salt Lake City’s MSA grew 8% and was a standout nationally.
The metro currently ranks number 32 nationally by inventory count.
In contrast, New York’s Manhattan hosts 270 coworking spaces, Chicago 269, Denver 239, and Las Vegas 75, according to Yardi data.
Square footage counts – how do they compare?
Even though the number of locations held steady in the SLC MSA, total square footage increased slightly. Yardi reports that “Total coworking space in Salt Lake City grew to 1.92 million sq. ft., marking a 1% increase over Q4 2024 and ranking among the top 25 coworking markets for total flex space size.”
Yardi’s geographical catchment area is quite large, and “spans parts of Salt Lake, Utah, Davis, Weber, and nearby counties to reflect the full coworking footprint in the region,” a company representative told us.
To put that in scale with traditional office space where revenues come from leases instead of memberships: Downtown Salt Lake City, which includes the Central Business District and periphery, offers over 12 million sf of rentable area according to CBRE’s latest office market report.
Suburban Salt Lake County adds nearly 29 million sf of available leasable space to the Downtown volume. That 41 million sf of traditionally-leasable space dwarfs Yardi’s generous coworking number (1.9 million) by a greater than 21:1 ratio – representing a small niche in the office market.
Yet that’s not insignificant, according to a prominent local broker.
How’s the local leasing market looking?
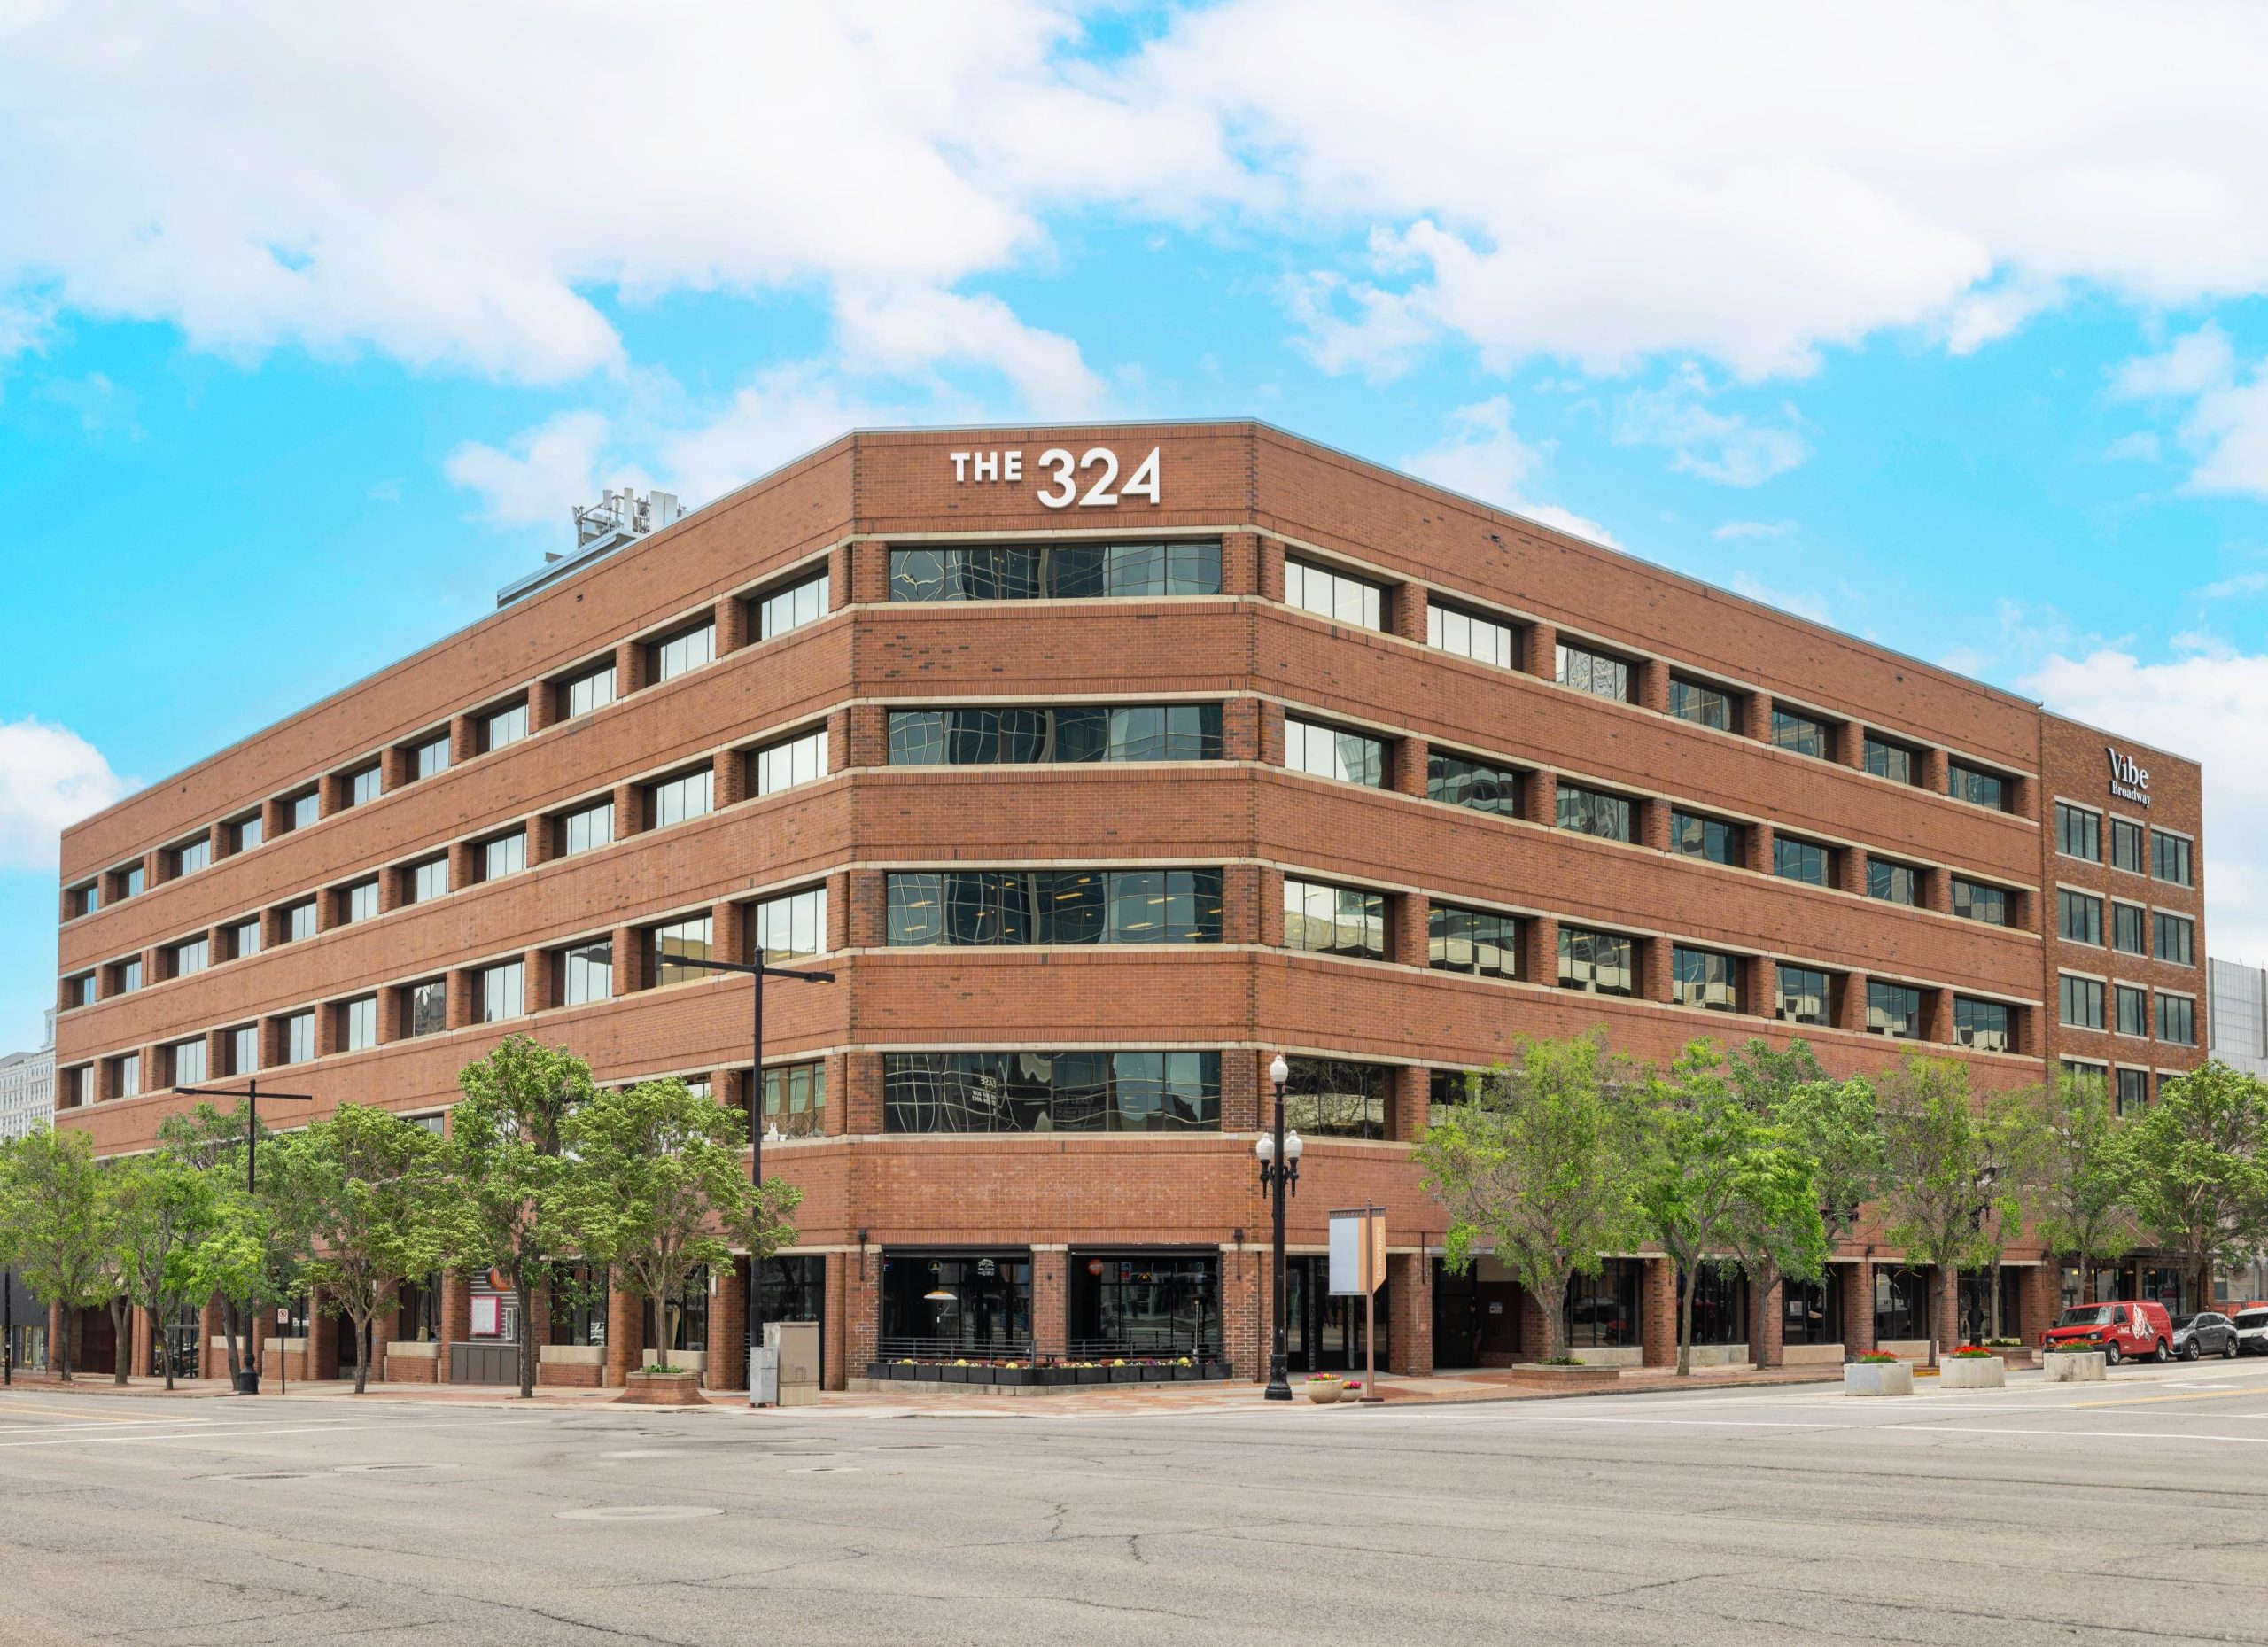
As we’ve reported recently, absorption is up in the SLC market, largely driven by Downtown leases, in both highly-amenitized Class A space as well as Class B space that has upped its game, like the 40,000 sf recently leased to energy company HF Sinclair at 324 S State (pictured above).
Nadia Letey, a senior vice president at CBRE specializing in office, told us that “we don’t really see coworking as a threat. Those spaces offer important options to companies who are just dipping their feet in the market, or who want to be Downtown but want a shorter commitment.”
Letey reaffirmed the “flight to quality” narrative that is providing the scarce positive news in the traditional office market. She estimates that given consistent demand, new leases currently being negotiated, limited inventory, and nearly no new construction, “options are going to dwindle for Class A space by year’s end.”
In addition, rents for amenity-rich Class A space are projected to increase. “We are hearing that lease rates will be higher in new builds,” she says.
Yet when might investors make a move for a new office tower, which, given demand, is likely to be Downtown?
Sundial Tower, at 450 S. Main, a partnership between Hines and JLL, the only office tower currently proposed Downtown, is on hold.

The West Quarter also has office space planned for future phases, which are also on hold, Ryan Ritchie told us, until Smith Entertainment Group finalizes their development mix at their Delta Center anchored sports and entertainment district.

Given the apparent office apocalypse, it might be a while before another big splash in construction, even given the demand for Class A+ space. Letey hears that banks are demanding financing terms that include significant pre-leases, like 50%.
In a shifting environment, where downsizing and short-term commitments are becoming more popular, we will have to see whether a 50% pre-lease requirement from banks is poison pill for the changing office market.







0 Comments