

As the woes of the office market continue to populate CRE headlines nationwide, cut-rate building sales and 25% availability rates are raising fewer eyebrows these days.
When we last reported on the Salt Lake City metro market’s performance a year ago, vacancy rates had hit an all-time high and lease rates were down nearly 5%.
Let’s take a look at how 2024 shaped up, thanks to CBRE’s Salt Lake City – Provo Office Q4 numbers and Mountain West CRE’s Year-End Market Report.
Vacancy / availability
Vacancy rates hit an historic high in Q3 2024, reaching 24.2%, and ending the year at 23.7%, according to CBRE. The vacancy rate measures how much of building’s available space is unoccupied, while availability rate measures vacancy plus spaces that may be occupied but are for lease, which includes the sublease market. At the end of 2024 availability stood at 25.3%.
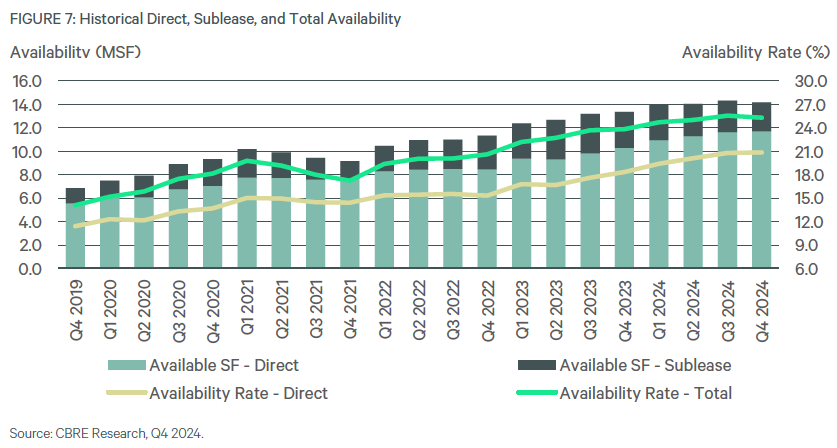
While vacancy and availability rates broke records for the second straight year, there are signs that the reduction seen in Q4 is likely to continue. As we touch on below, construction is at a virtual standstill and subleasing activity, after reaching 5-year highs, is on the decline.
Absorption
The Salt Lake – Provo market showed positive absorption in 2024 for the first time in two years.
CBRE numbers show, however, that the demand for space is concentrated in amenity-rich Class A space, while Class B and C properties are still bleeding.
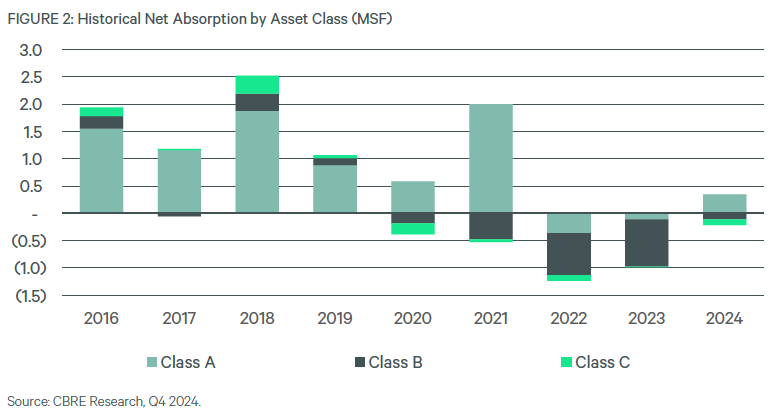
Year-over-year Class A properties added nearly 350,000 SF of absorption, enough to push the entire office market into the positive for the year. Tennant attrition, however, continues to haunt Class B and C spaces.
Rent rates
Average rent seems to have stabilized (down only 0.5% Y-o-Y), after a full nine quarters of declines.
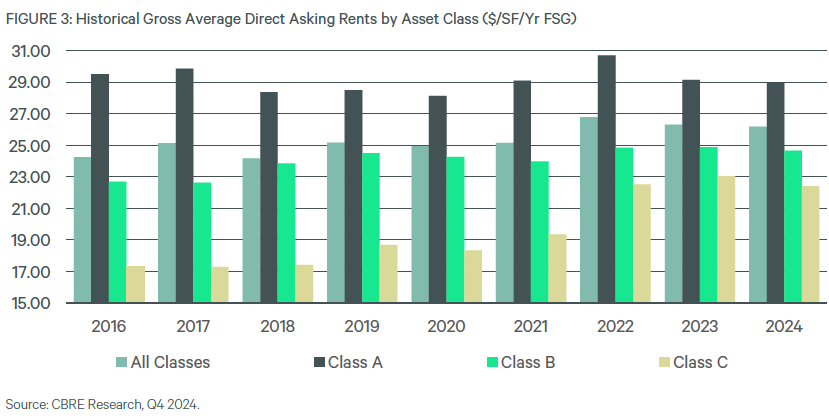
Asking Rent rates for Class A space ended the year at $29/SF for direct leases, while the average for all spaces opened 2025 at $26.18. Sub-lease rates averaged $23.42. CBRE analysts conclude that prospective office tenants continue to have the upper hand in negotiations given the wide availability of discounted sub-leases.
Lease activity
2024 was a good year for leasing activity, which was up 11.1% Y-o-Y. Class A leasing dominated the year’s leasing activity, accounting for 66% of new leases signed. Total leasing volume for the year in the Salt Lake – Provo market was 4.22 million SF.
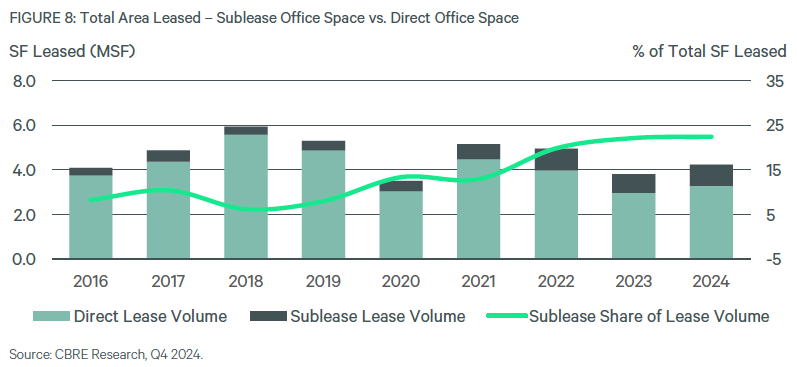
The Central Business District and Periphery accounted for most of that activity, followed by Lehi, Sandy South Towne, and Draper.
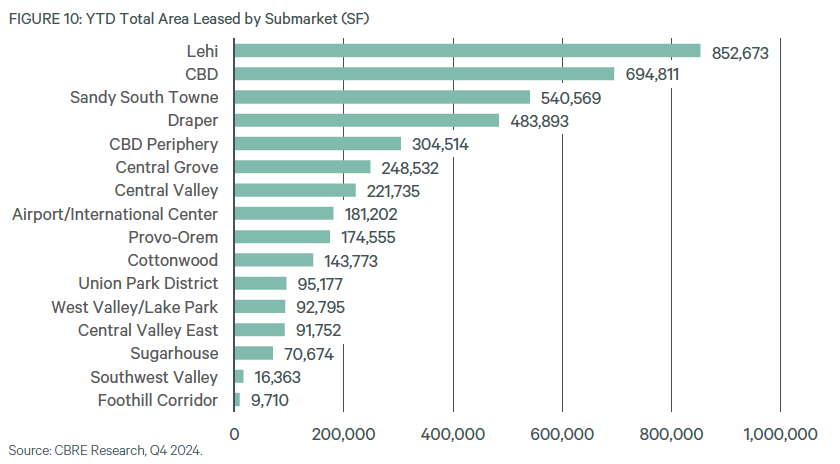
Sublease activity, on the rise since 2021, accounted for nearly a quarter of all lease transactions last year. “Class B and C properties face challenges and will need renovations and new amenities to stay competitive in a saturated sub-lease market,” comments MWCRE’s Peter Black.
Sales activity
Sales activity, in a climate of depressed demand and high financing costs, was dominated by government and education institution relocations. Owner-user acquisition was the trends.
The University of Utah acquired the City Centre building in Downtown, as Salt Lake County government prepares to decamp to the former Overstock.com campus. Canyons School District and Summit County also purchased discounted office buildings for their new headquarters.
Development activity
No new projects broke ground in 2024, while only 246,000 SF of new product was delivered over three properties.
CBRE analysts Matthew Smith and Sierra Hoffer postulate, “As occupiers continue to seek top-tier office buildings that create collaborative and inviting workspaces, the demand for Class A space will likely continue to outpace the lower levels of new supply in the near term, further strengthening top-tier office market fundamentals in 2025.”
Is there a way out of permanent 20-25% vacancy?
Increasingly, the future of the Class B and C office space looks to be residential. Either in conversion, also called adaptive reuse, or teardown and replacement with housing.
RentCafe released a report this month touting the nationwide trend in office-to-residential conversions, which have risen from 23,100 new apartments created in 2022 to a projected 70,700 in 2025.
Locally, the movement also seems to be picking up momentum. There are five projects currently under construction or recently completed in the Downtown and East Central neighborhoods:
•University Club Tower,136 E S Temple, now the Seraph
•IBM building, 348 E S Temple
•Medical Towers, 1060 E 100 S, now Victory Heights
•Medical Dental Building, 508 E S Temple, now Maye House
•HK Building, 515 E 100 S, now the 515 Tower
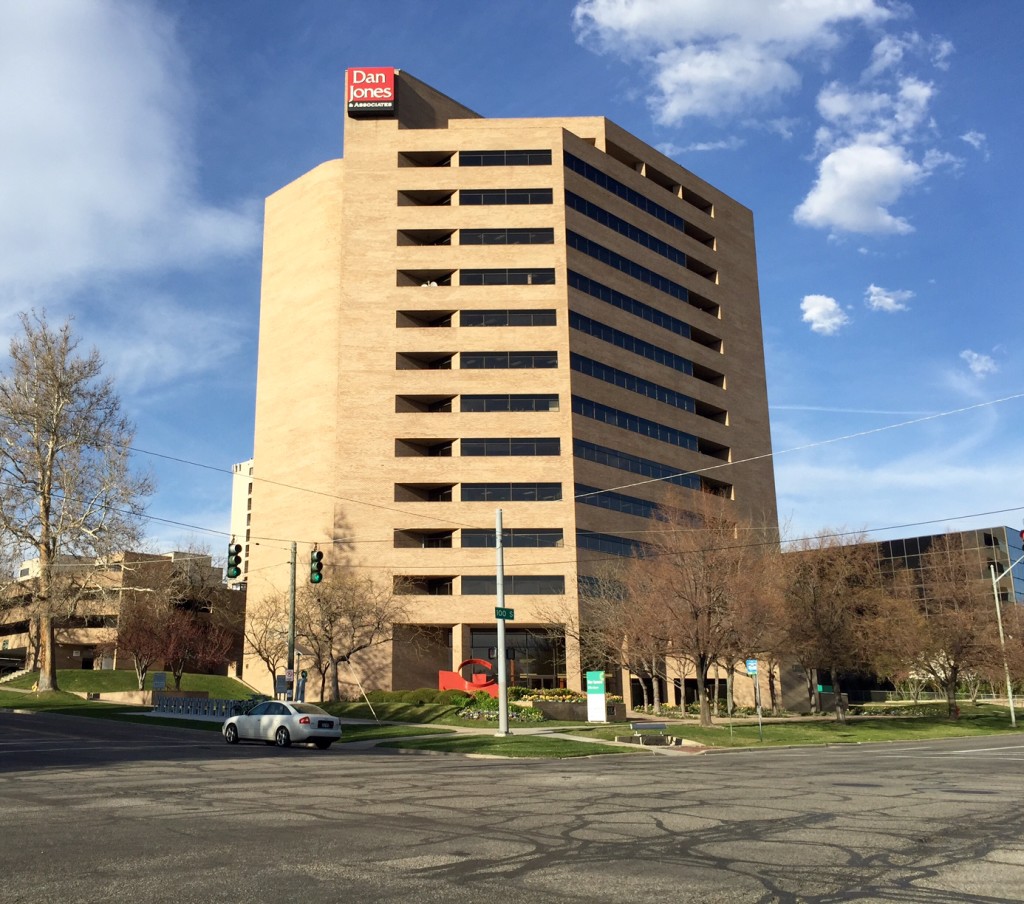
RentCafe claims 768 units will be completed in 2025 from former office spaces locally, up from 668 new apartments in 2024.
Many architects and developers, however, cite the design challenges facing office-to-residential conversions. The large floor plates of many office building make providing enough light to interior rooms difficult if not impossible.
















0 Comments